Only 7 places remaining

Your name on the mortgage, not mine. And I'll pay it myself, plus £50 a month, until your tenant moves in. You own the house from day one. We find it, guide you through buying it, refurbish it and let it.

This is a one-to-one portfolio building service, built for money that's been sitting still for longer than it should have. Your own solicitor if you'd rather use one, your own mortgage, and if Midas stopped trading the day after completion, you'd still own a tenanted house. That's how sure I am of the houses we pick.

The Protection Promise Paid every month from completion day, with no time limit on it. A cap would turn a promise into a term.
Bring whoever you'd normally ask about this afterwards, onto the call from the start. Son, daughter, doesn't matter who. I'd rather answer their questions to your face than have you answer them for me later.
Two ways to own a rental property

One of these leaves you working it out on your own. The other one pays you from completion day.

On your own

Working it out without anyone to check it for you

And every gap in the explanation feels like something to worry about.

  • You're relying on one salesperson's word for what a house is genuinely worth.
  • You quietly wonder what happens to it all if you're not the one managing it any more.
  • The refurbishment runs over, nobody explains why, and you don't know enough to argue.
  • Your son or daughter hears about it after you've signed, not before, and asks the question you couldn't answer.
  • You're carrying the mortgage alone until a tenant turns up, however long that takes.

With Midas

We do the hard part. Your name stays on everything.

And you're being paid before your tenant has picked up the keys.

  • We find it. The right area for what you're actually trying to do, not what's convenient for us.
  • We value and negotiate it. Same tools the agents use, so you're not taking anyone's word for it.
  • Your name goes on it. Your own solicitor if you'd rather, your own mortgage, your house.
  • We refurbish it. Our own trades, our own project manager, every certificate in place.
  • We pay you until your tenant does. Your mortgage covered plus £50 a month, from completion day until they move in.

March 2021 to May 2026

Is your money working for you, or against you?

Think back five years to what you had put away. Do you feel richer than you did, or poorer? Most money sitting in the bank is losing the race against inflation, quietly, and the statement never says so. Here's what those five years did to £200,000, depending entirely on where somebody left it.

Left in the bank

Poorer

£153,652

What your £200,000 will actually buy you now.

The statement still says two hundred grand and nothing appears to have gone wrong. Prices rose 30.2% while it sat there, so £46,348 of what it could buy has walked off. Safe and still aren't the same thing.

One house, a real one

Richer

£131,537

Equity, from £44,487 down.

Bought March 2021 for £177,950. Valued at £265,000 in May 2026. The deposit very nearly tripled, and that's before a single month of the rent it paid along the way.

Best of the three

The same £200,000, working

Richest

£526,148

Equity by May 2026, from four deposits.

Four deposits at £44,487 comes to £177,948. The £22,052 left over goes towards buying costs, which aren't in this sum. The figure is arithmetic, the house beside it four times over, and it counts no rent whatsoever.

Inflation figures are the Office for National Statistics Consumer Prices Index, which read 109.4 in March 2021 and 142.4 in May 2026.

The house those numbers come from

A real purchase, not an example.

Bought, March 2021£177,950
Deposit£44,487
Mortgage£133,463
Valued, May 2026£265,000
Equity, May 2026£131,537

Three things that make that figure smaller rather than bigger, because you'd only ask. The mortgage is treated as interest only, so nothing has come off the balance. Buying costs and refurbishment sit on top of the deposit and are not in the sum. And no rent is counted anywhere in it.

It isn't the only one

Bought within weeks of the one above. Same tenant from day one, never changed.

Bought, 2021£84,500
Deposit£21,125
Mortgage£63,375
Rent, since 2021£660 → £720
Valued, April 2024£118,000
Equity, April 2024£54,625

Same rules as the house above. Mortgage treated as interest only. Stamp duty (£2,535) and refurbishment (about £7,500) sat on top of the deposit and aren't in this sum. The valuation is from April 2024, agreed alongside a rent review, not fetched fresh for this page. And the same tenant has been in since the day it was let, so there's been no void to pay for either.

So the only question left is where you'd like to be in five years.

How we work

We call it RENT, because that's what it makes you.

Research

National, local and street level trends, read properly. Areas matched to your goal, not to which one we happen to know. Where you end up depends on what your money has to do, and that gets decided after we understand your circumstances, not before. You don't need to know the area. That's the part you're employing us for, and we own where we recommend. We also watch what the government is likely to do next, so your plan is built to survive it rather than be surprised by it.

Evaluate

We have the same valuation tools the estate agents have. What houses actually sell for, how long they sit, how many get their asking price. So you know what a property is genuinely worth before you offer, not what somebody hopes it's worth.

Negotiate

Direct to the vendor or through the agent, we do the arguing. Then we do it again with the trades. The work is priced and specified before we make an offer, so the number doesn't move on you halfway through. Our teams work with us regularly and they know the standard and the price we accept, so you're not paying the stranger tax on either end.

Tenant time

Listings on every major platform, enquiries and viewings handled, rent set at what your house can genuinely achieve. Everybody concentrates on getting somebody in. The work is in who you let in, so applicants are interviewed, referenced, and we take a guarantor every time, which means if the rent ever stops there is somebody else answerable for it. All the paperwork done properly, which is the boring stuff that keeps the rent coming in.

The hard part, done for you.

I charge a fee per property, and you'll have it in writing before you commit to anything.

I slept in my car so my kids could keep their home.

I had a career in television that I loved, a fiancée of ten years, three children and a house in a lovely area. Then my boss sat me down and told me the company couldn't afford me. One month's notice, one month's salary, and the main income my family had was gone.

What followed very nearly took the lot. The relationship went, and I moved out of the family home. I kept paying the mortgage on a house I no longer lived in, because my children were still in it, and I slept in my car, on sofas, and on an air mattress in the properties I was doing up.

I made myself a promise in that car. Never one income again. And always a roof I could offer somebody I love.

I've been investing for eight years now, and doing it for other people for seven. I'm not special and I've no interest in pretending otherwise. I'm an ordinary bloke who had to learn how to find a good house and refurbish it cheaply because I was skint and couldn't afford to get it wrong. That's the system you'd be getting, and it's the one I wish somebody had handed me when I was sleeping in that car.

8

Years investing in property.

7

Years sourcing and packaging deals for other people.

100%

Yours. The house goes in your name or your company's, never ours.

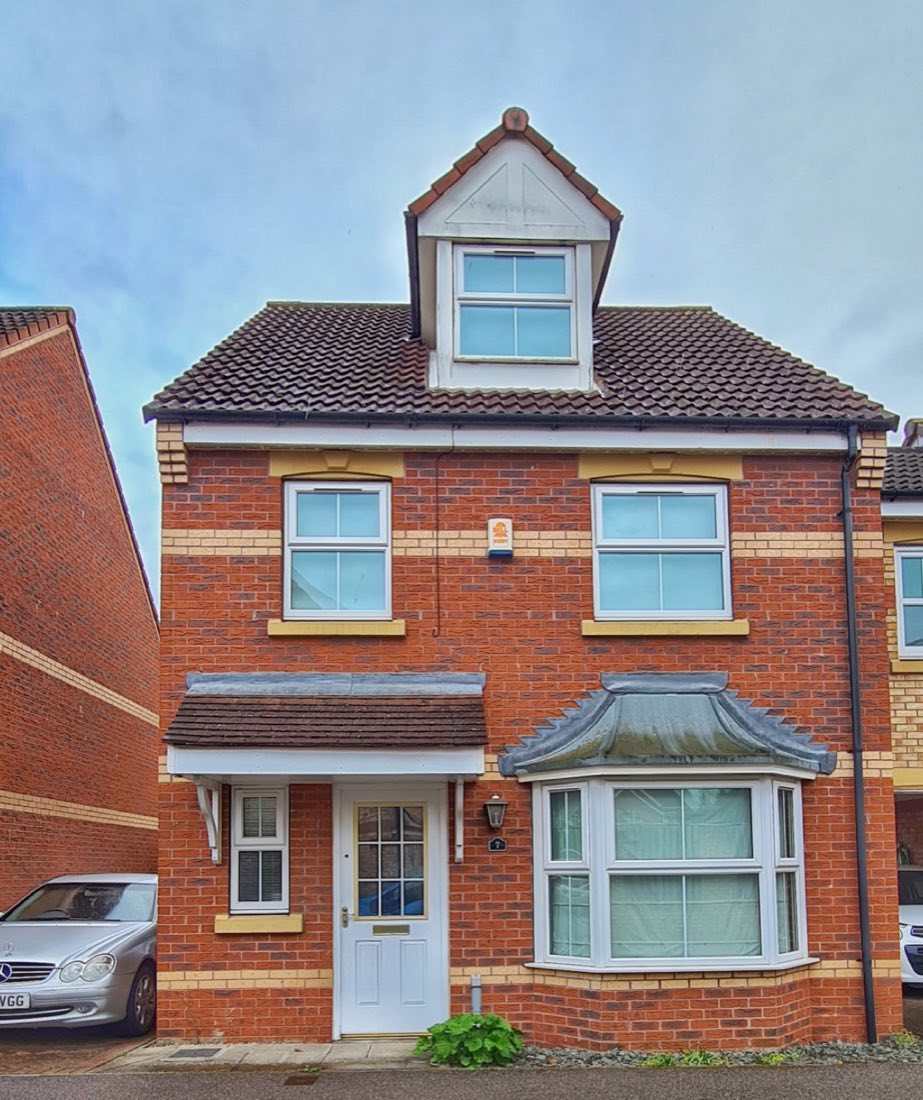
A three-storey red brick house with a bay window and a white front door, one of the properties Ryan owns and lets.

What happens next

One call. Thirty minutes. Free. Take whoever you'd like on it.

What you have, what you want it earning, how soon, and what you're actually building it for. No property gets mentioned. If property's the wrong home for your money, that's the call where I tell you.

There's no deadline on making a decision beyond the seven places themselves. Go away and think about it, talk to whoever you'd normally talk to, and come back when you're ready. If it's a fit, we keep going from there with a written Financial Freedom Plan, real numbers, completed deals shown rather than talked about, and none of it costs you anything.

Why there is a number on this

Seven clients, then this page comes down.

7

Places, and not one more.

I write every plan myself and my own teams run every refurbishment. Seven is what I can carry and still do properly. When the seventh is taken this offer comes off, and anybody after that gets told exactly where they stand rather than waved through.

That's a real limit on my time, not a deadline on your decision. Take as long as you need to talk it over; the only thing that runs out is the seventh place.

Book the call if

  • You have money that's been sitting still for longer than it should have, and you've known it for a while.
  • You want your own name on the mortgage and your own solicitor holding the paperwork.
  • You'd rather bring someone else onto the call than make the decision alone.
  • You want a plan that's honest about what happens if your circumstances change.
  • You want the income starting soon rather than one day.

Don't book it if

  • You want to learn to manage a rental yourself. Fair enough, and there are cheaper ways to learn.
  • You need the money back inside a year. Property doesn't move at that speed.
  • You want a guaranteed return. I won't give you one, and be wary of anybody who does.
  • You need to decide today. Take the time you need; nothing here is time-limited beyond the seven places.

Where do you want this to be in five years, and who do you want it to matter to?

Give me your name and a number and we'll start with a call about what you've actually got. Bring whoever you'd like. Everything after that gets built round your answer, and nothing gets decided in that first thirty minutes but whether it's worth a second one.