Only 7 places remaining

You get the house. You get the rent. And until your tenant moves in, I pay your mortgage, plus £50 a month. I start with what your money has to do, then find the house that does it, buy it in your name, refurbish it and let it.

For business owners and professionals with money sitting in the bank losing the race against inflation, and no evenings to spare. I've more than 30 houses of my own. I'm doing for you what I've already done for myself.

The Protection Promise For my first 7 clients, on the first house we buy together. Paid every month from completion day, with no time limit on it. A cap would turn a promise into a term.
How it works

The Midas Money Method: your money first, the house second.

Most people start with a house that happened to be for sale that week. I start with what your money has to do, and only then go looking.

Map

What you need coming in each month, worked out from your outgoings, and what your money can realistically do. We go through the numbers together on the call, and once you sign it goes in writing as your Midas Money Map.

Match

Areas matched to your goal, then a house that stands up to the research. I value it on the same tools estate agents use and negotiate it with the vendor or the agent.

Mortgage

If you're borrowing, you meet a broker before any search starts, so you see what it costs before you commit to anything. The mortgage advice is theirs, not mine.

Modernise

The refurbishment is scoped and priced before the offer goes in, and the number doesn't move. Gas, electrics, EPC and alarms all signed off.

Move-in

A tenant found and referenced, and a written update from me every fortnight from the day you sign, so you never have to chase. For my first 7 clients, on the first house, I pay your mortgage plus £50 a month from completion day until your tenant moves in.

I charge a fee per property, and you'll have it in writing before you commit to anything.

Two ways to own a rental property

One of these costs you your evenings and a decade of patience. The other one pays you from completion day.

On your own

Jobs you've never done before

And every one of them expensive to get wrong.

  • You buy within twenty minutes of home, because that's the area you know and that's what was for sale that week.
  • You pay what the agent asks, because you've no way of knowing what the house is genuinely worth.
  • I've watched inexperience add 15 to 25 per cent to the cost of the works. Nobody plans to spend that.
  • Evenings on the phone to a plasterer in a town you've no reason to be in.
  • Then you pay the mortgage yourself, month after month, until somebody finally moves in.

With Midas

We do the hard part. You own the house.

And you're being paid before your tenant has picked up the keys.

  • Your mortgage paid until your tenant moves in. Plus £50 a month from completion day, for my first 7 clients, on the first house we buy together.

March 2021 to May 2026

Is your money working for you, or against you?

Think back five years to what you had put away. Do you feel richer than you did, or poorer? Most money sitting in the bank is losing the race against inflation, and the statement never says so. Here's what those five years did to £200,000, depending entirely on where somebody left it.

Left in the bank, before interest

Poorer

£153,652

What £200,000 kept in cash buys now, before any interest it earned.

Prices rose 30.2% while it sat there. Interest claws some of that back, but an average easy-access account didn't keep pace.

One house, a real one

Richer

£131,537

Equity, from £44,487 down.

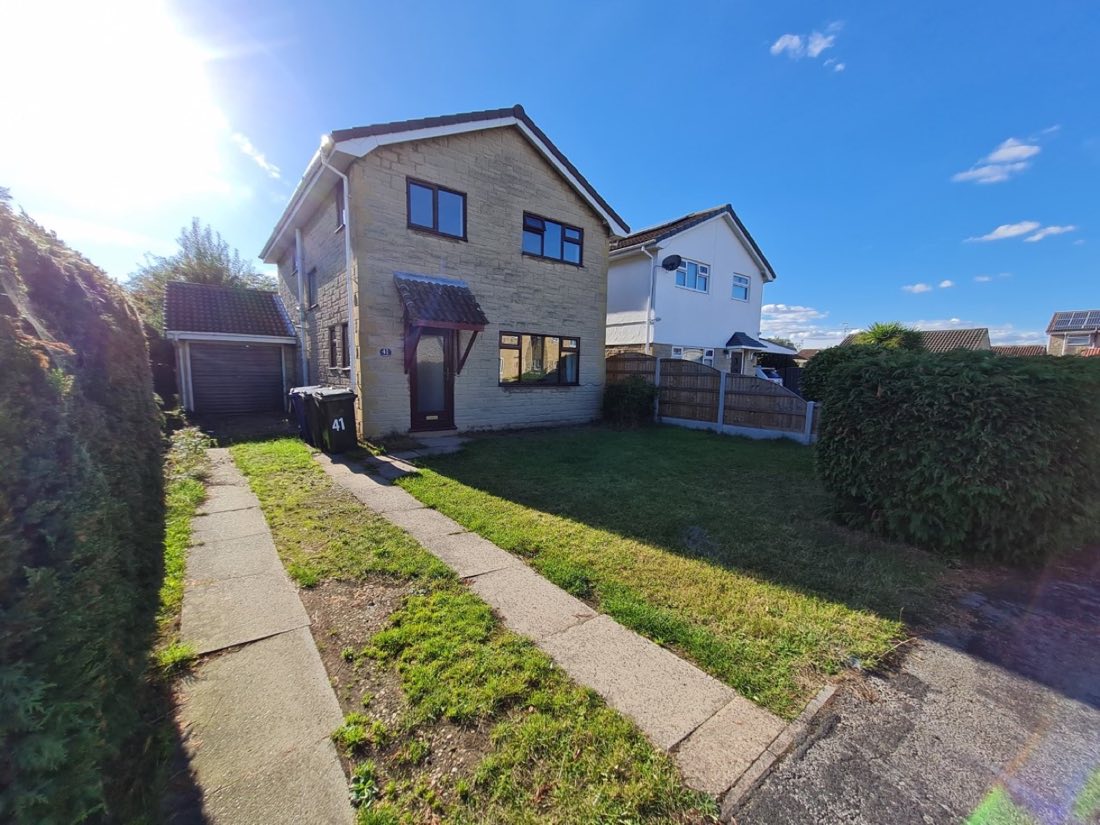
Bought March 2021 for £177,950. Valued at £265,000 by the lender in May 2026. Buying costs and the refurbishment came on top of the £44,487 deposit, and the rent it's paid since isn't counted.

Yours

Work out what your own savings have lost, interest and all, from your own figures and the official index. It takes 60 seconds.

Work out my number

Inflation figures are the Office for National Statistics Consumer Prices Index, which read 109.4 in March 2021 and 142.4 in May 2026.

The house those numbers come from

A real purchase, not an example.

Bought, March 2021£177,950
Deposit£44,487
Mortgage£133,463
Valued, May 2026£265,000
Equity, May 2026£131,537

Three things to know about that figure. The mortgage is treated as interest only, so nothing has come off the balance. Buying costs and the refurbishment came on top of the deposit and aren't in the sum, so the cash that went in was more than £44,487. And no rent is counted anywhere in it.

So the only question left is where you'd like to be in five years.

How we work

We call it RENT, because that's what it makes you.

Research

National, local and street level trends, read properly. Areas matched to your goal, not to which one we happen to know. Where you end up depends on what your money has to do, and that gets decided after we understand your circumstances, not before. You don't need to know the area. That's the part you're employing us for, and we own where we recommend. We also watch what the government is likely to do next, so your plan is built to survive it rather than be surprised by it.

Evaluate

We have the same valuation tools the estate agents have. What houses actually sell for, how long they sit, how many get their asking price. So you know what a property is genuinely worth before you offer, not what somebody hopes it's worth.

Negotiate

Direct to the vendor or through the agent, we do the arguing. Then we do it again with the trades. The work is priced and specified before we make an offer, so the number doesn't move on you halfway through. Our teams work with us regularly and they know the standard and the price we accept, so you're not paying the stranger tax on either end.

Tenant time

Listings on every major platform, enquiries and viewings handled, rent set at what your house can genuinely achieve. Everybody concentrates on getting somebody in. The work is in who you let in, so applicants are interviewed and referenced, through the managing agent you choose. All the paperwork done properly, which is the boring stuff that keeps the rent coming in.

I slept in my car so my kids could keep their home.

I had a career in television that I loved, a fiancée of ten years, three children and a house in a lovely area. Then my boss sat me down and told me the company couldn't afford me. One month's notice, one month's salary, and the main income my family had was gone.

What followed very nearly took the lot. The relationship went, and I moved out of the family home. I kept paying the mortgage on a house I no longer lived in, because my children were still in it, and I slept in my car, on sofas, and on an air mattress in the properties I was doing up.

I made myself a promise in that car. Never one income again. And always a roof I could offer somebody I love.

I've been investing since 2017, and doing it for other people for seven years. I'm not special and I've no interest in pretending otherwise. I'm an ordinary bloke who had to learn how to find a good house and refurbish it cheaply because I was skint and couldn't afford to get it wrong. That's the system you'd be getting, and it's the one I wish somebody had handed me when I was sleeping in that car.

2017

Investing in property since

7

Years sourcing and packaging deals for other people.

100%

Yours. The house goes in your name or your company's, never ours.

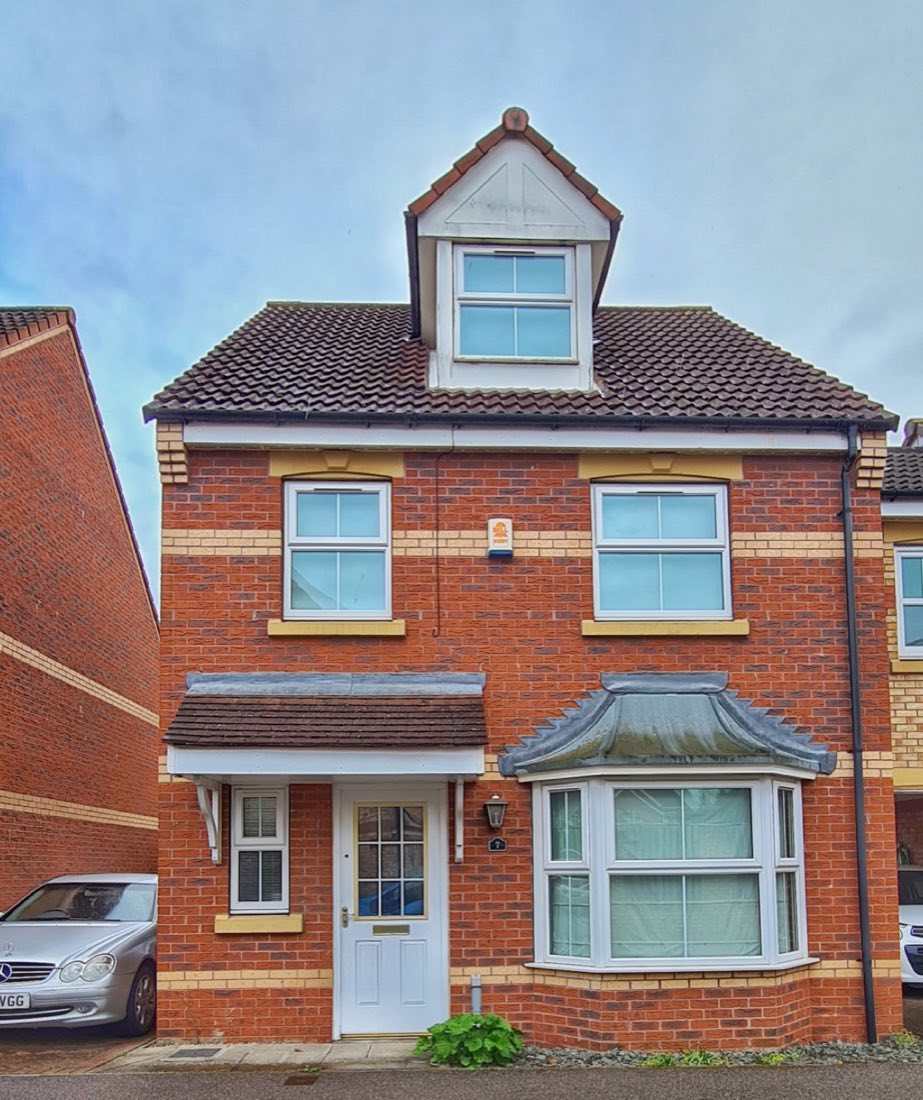
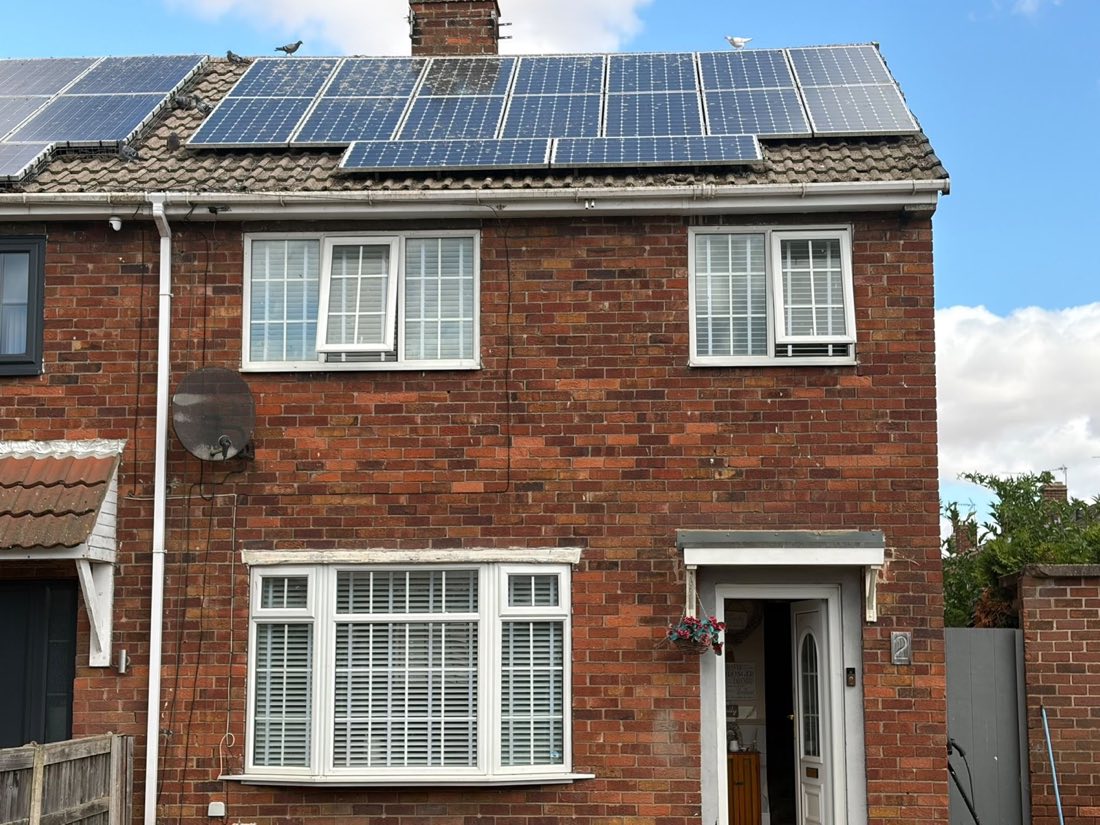
A three-storey red brick house with a bay window and a white front door, one of the properties Ryan owns and lets.

What happens next

One call. Thirty minutes. Free.

What you have, what you want it earning, how soon, and what you're actually building it for. No property gets mentioned. If property's the wrong home for your money, that's the call where I tell you.

If it's a fit, we keep going from there. Real numbers for your situation and completed deals shown rather than talked about. The calls cost you nothing. If you go ahead, you'll have my fee in writing before you commit to anything. Once you sign, your Midas Money Map comes next.

Why there is a number on this

Seven places. When they're gone, the promise goes with them.

7

Places, and not one more.

The Protection Promise is for my first seven clients only, on the first house we buy together. I won't be offering it again.

You've got time to think it over, and you should use it. I'd only say this: seven isn't many, and I don't expect them to last.

Book the call if

  • You have money sitting in the bank losing the race against inflation, and you've known about it a while.
  • You want a plan built round you, not a house sold at you.
  • You're happy owning it yourself, your name or your company's.
  • You'd rather somebody else held the plasterer's phone number.
  • You want it started this year, done properly.

Don't book it if

  • You want to learn to do this yourself. Fair enough, and there are cheaper ways to learn.
  • You need the money back inside a year. Property doesn't move at that speed.
  • You want to be promised a figure before you start. Cash flow is forecast and growth is expected, and I won't dress either up as a promise.
  • You'd want to be on every call with the builder. You'd be paying me to duplicate you.

Where do you want to be in five years?

Give me your name and a phone number and we'll start with a call about what you've actually got. Everything after that gets built round your answer. Property doesn't get made redundant.