I've paid a mortgage on a house I didn't live in. Now I'll pay yours, plus £50 a month, until your tenant moves in.
You own the house. We find it, guide you through buying it, refurbish it and let it.
This is a bespoke portfolio building service, and it's built for money that's sitting in the bank losing the race against inflation. From completion day until your tenant moves in, your mortgage is mine to pay. That's how sure I am of the houses we pick.
The Protection PromisePaid every month from completion day, with no time limit on it. A cap would turn a promise into a term.
Think back five years to what you had put away. Do you feel richer than you did, or poorer? Most money sitting in the bank is losing the race against inflation, and the statement never says so. Here's what those five years did to £200,000, depending entirely on where somebody left it.
Left in the bank
Poorer
£153,652
What your £200,000 will actually buy you now.
The statement still says two hundred grand and nothing appears to have gone wrong. Prices rose 30.2% while it sat there, so £46,348 of what it could buy has walked off. Safe and still aren't the same thing.
One house, a real one
Richer
£131,537
Equity, from £44,487 down.
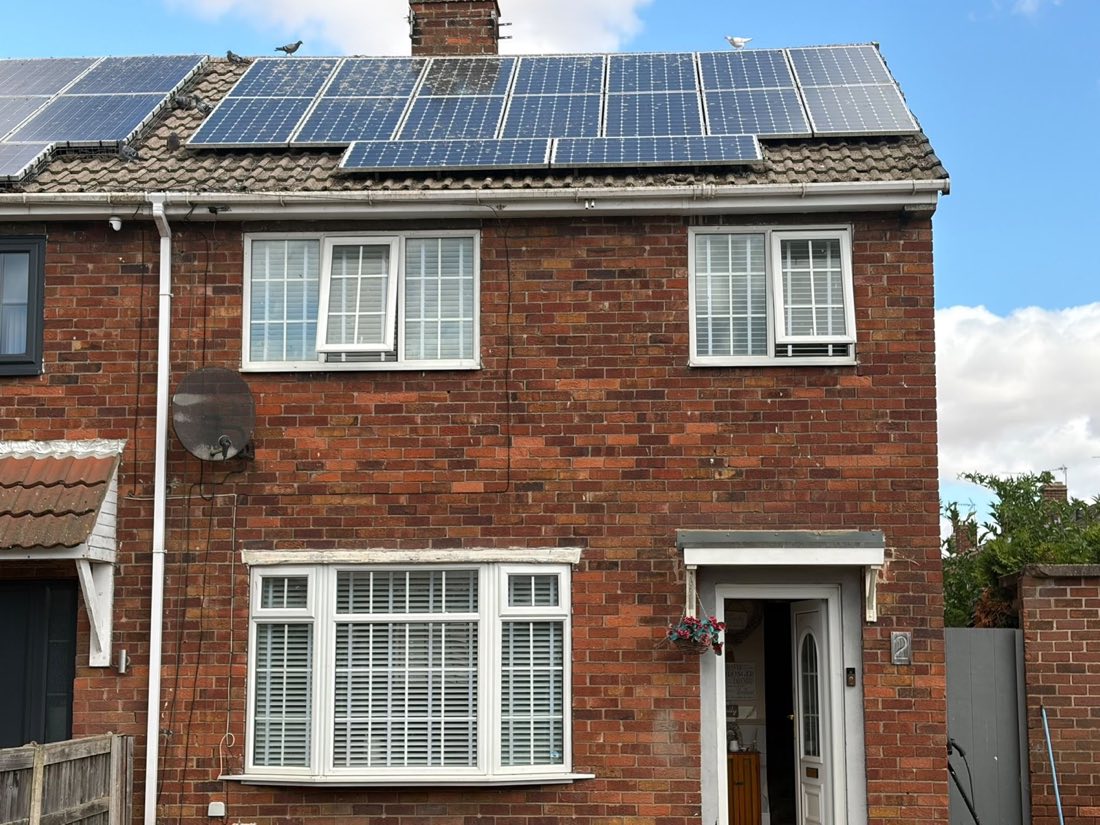
Bought March 2021 for £177,950. Valued at £265,000 in May 2026. The deposit very nearly tripled, and that's before a single month of the rent it paid along the way.
Best of the three
The same £200,000, working
Richest
£526,148
Equity by May 2026, from four deposits.
Four deposits at £44,487 comes to £177,948. The £22,052 left over goes towards buying costs, which aren't in this sum. The figure is arithmetic, the house beside it four times over, and it counts no rent whatsoever.
Inflation figures are the Office for National Statistics Consumer Prices Index, which read 109.4 in March 2021 and 142.4 in May 2026.
The house those numbers come from
A real purchase, not an example.
Bought, March 2021£177,950
Deposit£44,487
Mortgage£133,463
Valued, May 2026£265,000
Equity, May 2026£131,537
Three things that make that figure smaller rather than bigger, because you'd only ask. The mortgage is treated as interest only, so nothing has come off the balance. Buying costs and refurbishment sit on top of the deposit and are not in the sum. And no rent is counted anywhere in it.
So the only question left is where you'd like to be in five years.
We call it RENT, because that's what it makes you.
R
Research
National, local and street level trends, read properly. Which areas suit your goal rather than which area we happen to know. We also watch what the government is likely to do next, so your plan is built to survive it rather than be surprised by it.
E
Evaluate
We have the same valuation tools the estate agents have. What houses actually sell for, how long they sit, how many get their asking price. So you know what a property is genuinely worth before you offer, not what somebody hopes it's worth.
N
Negotiate
Direct to the vendor or through the agent, we do the arguing. Then we do it again with the trades. Our teams work with us regularly and they know the standard and the price we accept, so you're not paying the stranger tax on either end.
T
Tenant time
Listings on every major platform, enquiries and viewings handled, rent set at what your house can genuinely achieve. Applicants interviewed and referenced. All the paperwork done properly, which is the boring stuff that keeps the rent coming in.
The hard part, done for you.
1
Understand youGoals, budget and timeline
2
Find the dealsSourced against your criteria
3
Value it correctlyMarket, tenant demand and risk, all checked
4
Negotiate the purchaseWith the vendor or through the agent
5
FinanceArranged with trusted brokers
6
ConveyancingManaged to the keys, our solicitor or yours
7
RefurbishmentProject managed and certified
8
TenancyFound, referenced and managed
Who you'd be working with
I slept in my car so my kids could keep their home.
I had a career in television that I loved, a fiancée of ten years, three children and a house in a lovely area. Then my boss sat me down and told me the company couldn't afford me. One month's notice, one month's salary, and the main income my family had was gone.
What followed very nearly took the lot. The relationship went, and I moved out of the family home. I kept paying the mortgage on a house I no longer lived in, because my children were still in it, and I slept in my car, on sofas, and on an air mattress in the properties I was doing up.
I made myself a promise in that car. Never one income again. And always a roof I could offer somebody I love.
I've been investing for eight years now, and doing it for other people for seven. I'm not special and I've no interest in pretending otherwise. I'm an ordinary bloke who had to learn how to find a good house and refurbish it cheaply because I was skint and couldn't afford to get it wrong. That's the system you'd be getting, and it's the one I wish somebody had handed me when I was sleeping in that car.
8
Years investing in property.
7
Years sourcing and packaging deals for other people.
100%
Yours. The house goes in your name or your company's, never ours.
What happens next
One call. Thirty minutes. Free.
What you have, what you want it earning, how soon, and what you're actually building it for. No property gets mentioned. If property's the wrong home for your money, that's the call where I tell you.
If it's a fit, we keep going from there. A written Financial Freedom Plan with real numbers on it, completed deals shown rather than talked about, and none of it costs you anything. The plan is yours to keep even if you never buy a house through me.
Your Financial Freedom Plan, in writing
What your money can realistically produce, and how long it takes to get there.
The areas that suit your goal
Which of the areas we work in fits what you're after, and why that one over the others.
The numbers on the way there
What one house does for you, what four do, and what it takes to reach the income you named.
The order to buy in
What to buy first and what after, so each house makes the next one easier rather than harder.
Completed deals with real figures
Put in front of you on screen. Purchase price, works, valuation, rent.
A straight answer
If what you have won't get you where you want to be, I'll tell you rather than sell you something anyway.
I write every plan myself and my own teams run every refurbishment. Seven is what I can carry and still do properly. When the seventh is taken this offer comes off, and anybody after that gets told exactly where they stand rather than waved through.
I could take more than seven. I'd just have to stop doing them properly, and I won't.
Book the call if
You have money sitting in the bank losing the race against inflation, and you've known about it a while.
You want a plan built round you, not a house sold at you.
You're happy owning it yourself, your name or your company's.
You'd rather somebody else held the plasterer's phone number.
You want the income starting soon rather than one day.
Don't book it if
You want to learn to do this yourself. Fair enough, and there are cheaper ways to learn.
You need the money back inside a year. Property doesn't move at that speed.
You want a guaranteed return. I won't give you one, and be wary of anybody who does.
You'd want to be on every call with the builder. You'd be paying me to duplicate you.
Where do you want to be in five years?
Give me your name and a number and we'll start with a call about what you've actually got. Everything after that gets built round your answer. Property doesn't get made redundant, and neither does a plan that's yours to keep.